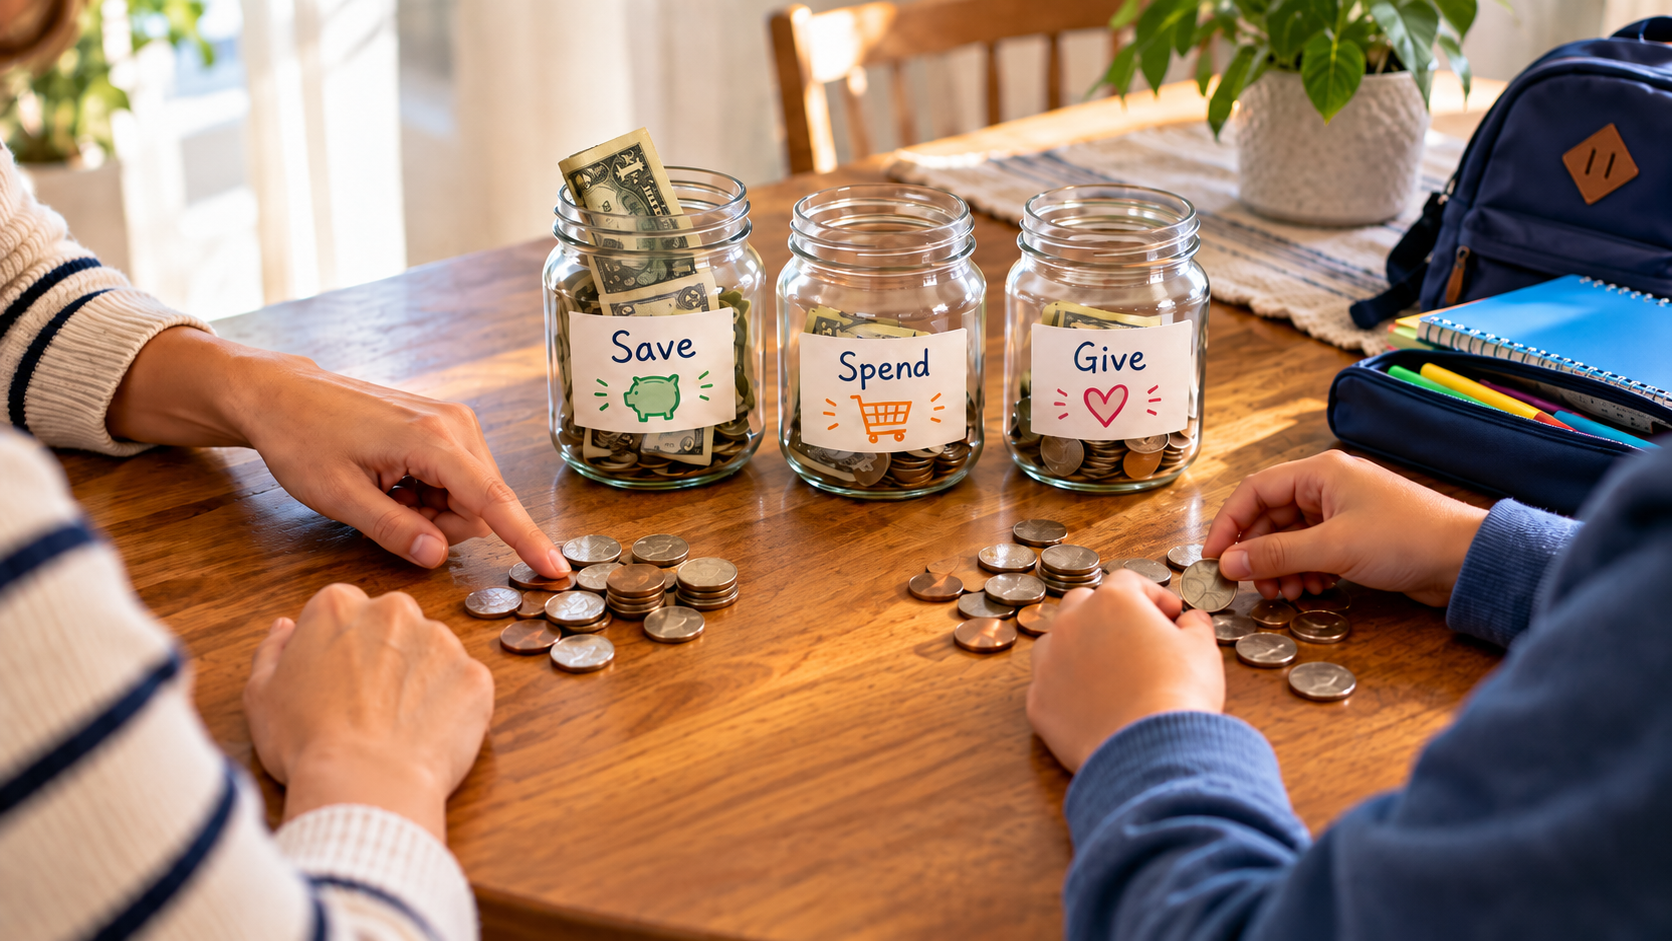
Every parent wants to help their children succeed. Whether it’s paying for college, helping with a first home, funding a wedding, or eventually leaving an inheritance, the motivation comes from a place of love.
Yet after working with families for more than two decades, I’ve noticed that the happiest families aren’t necessarily the ones who leave the largest inheritance. They’re the ones who raise children who understand the value of money, appreciate hard work, and develop the confidence to make good financial decisions on their own.
Money can create opportunities.
Character creates financial independence.
Here are a few ideas that can make a lasting impact:
Teach Them to Earn Before They Spend
It’s natural to want to provide for our kids. Yet earning something often creates a level of appreciation that simply receiving it never can. Whether it’s mowing lawns, babysitting, helping around the house, or working a summer job, earning teaches responsibility, pride, and confidence.
For business owners, there may be another opportunity. If your children legitimately work in your business, paying them a reasonable wage can introduce these lessons at an earlier age while also creating some financial planning opportunities.
Reward Good Habits
One of my favorite ideas is a “Roth Match.” If your teenage child (or grandchild) earns money from a part-time or summer job, help them open a Roth IRA and encourage them to contribute a portion of what they earn.
For example, if they make $3,000 lifeguarding or scooping ice cream and put $1,500 into a Roth IRA, you could match that contribution with another $1,500.
They learn the discipline of saving their own money, and your match rewards a smart financial decision while helping them start building wealth decades earlier than most people.
The same opportunity can apply to business owners whose children legitimately work in the business. Once they have earned income, they may be eligible to contribute to a Roth IRA. The amounts don’t need to be large. Giving a child the opportunity to start investing in their teens can give those dollars decades to grow.
Encourage Saving with a Purpose
Instead of saying, “You should save your money,” help your children identify a goal they’re excited about. Saving becomes much easier when there’s a reason behind it. Along the way, they’ll learn delayed gratification—a valuable skill that can serve them well throughout life.
Give Experiences, Not Just Things
Family vacations and excursions, educational opportunities, volunteering together, or helping pay for experiences often leave a deeper impression than another material purchase. Those memories frequently shape values just as much as they create enjoyment. (Some of our favorites: concert/show/game tickets, horseback riding, offshore fishing.)
Make Money a Normal Conversation
You don’t need to share every detail of your finances, yet children benefit tremendously from hearing age-appropriate conversations about budgeting, charitable giving, investing, and making thoughtful decisions. Money shouldn’t be a mystery.
Help…Without Removing Responsibility
Supporting your children through college, a first home purchase, or another major milestone can be incredibly meaningful. Yet, consider structuring that help in ways that encourage ownership rather than dependence. Sometimes contributing alongside your children teaches more than paying for everything yourself.
One day your children may inherit your assets. Long before that day arrives, they’ll inherit your habits, your values, and your example. In my experience, that’s the inheritance they’ll remember most.
Sometimes the greatest financial gift isn’t the money itself—it’s helping someone develop financial habits that will serve them for the rest of their life.