As parents get older, families often start thinking about how to protect their finances. Sometimes that conversation starts with adult children wondering how they can help. Other times, it starts with the parents themselves wanting to put safeguards in place.
Years ago, an advisor friend shared a story with Dennis that has stayed with him (and he has since passed on to me). An elderly woman with dementia was living in an assisted-living facility. An employee gained her trust, persuaded her to sign a Power of Attorney, and gradually isolated her from her family before using that access to take money from her bank accounts. Police got involved, and her family eventually stepped in, yet significant financial damage had already been done.
It’s an extreme example, and thankfully not something we see every day. Yet it highlights something important: fraud isn’t always a suspicious email from a stranger. Sometimes the greater risk is that someone vulnerable begins trusting the wrong person.
The best protection often starts long before there’s a problem—with family conversations, good planning, and a few simple safeguards.
Plan Ahead While Everyone Has a Voice
Talking about money as parents get older can be awkward. Parents who have successfully managed their finances for decades understandably don’t want to feel as though someone is suddenly looking over their shoulder. Adult children, meanwhile, may see potential risks yet hesitate to overstep.
 That’s exactly why the best time to have the conversation is before anyone needs help. The goal isn’t to take control. It’s to decide together what a financial safety net should look like while everyone can be thoughtful and intentional about it.
1. Have the Conversation Before There’s a Problem
Instead of waiting for a concern to arise, families can start with a simple question:
“If we ever became concerned that someone was taking advantage of you, what would you want us to do?”
A few questions worth discussing:
-
Who should be called first?
-
Which child or family member should take the lead?
-
Who are your financial advisor, CPA and attorney?
-
Where are your important financial and legal documents?
-
Who should know if something seems unusual?
These decisions are much easier when they’re made together, before emotions or urgency enter the picture.
2. Name Trusted Contacts and Turn On Alerts
Parents can consider naming trusted contacts with their financial institutions. A trusted contact generally doesn’t have authority to trade, withdraw money or control the account. Instead, it gives the financial institution someone to contact if there is concern about a client’s health, welfare or possible financial exploitation.
Technology can provide another layer of protection. Depending on the institution, alerts may be available for large withdrawals, wire transfers, unusual credit-card activity, password changes or other transactions. For some families, Mom and Dad may receive the alerts. In other situations, an adult child may appropriately be included.
The goal isn’t to monitor whether Dad spent $87 at the hardware store. It’s to make unusual activity harder to miss.
3. Create a Family “Stop and Call” Rule
Fraudsters are very good at creating urgency:
“Your grandson has been arrested.”
“There’s fraud on your bank account.”
“You owe the IRS money.”
“Your computer has been compromised.”
Technology is also making fraudulent calls, messages and impersonations increasingly convincing.
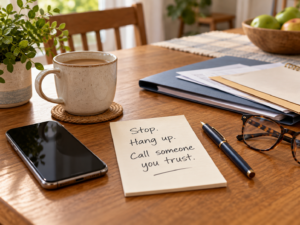 A simple Family Rule can help: Never send money or provide financial information based solely on an incoming call, text or email. Stop. Hang up. Call someone you trust.
If a bank supposedly called, call the bank back using a phone number you already know or obtain independently—not the number provided by the caller. There are very few legitimate financial emergencies that can’t survive a 10-minute call to a family member, advisor or other trusted person.
4. Have the Right Legal Documents AND the Right People
A Durable Power of Attorney can be an incredibly important planning document. Yet Dennis’ story illustrates the other side of it.
The document is only as trustworthy as the person receiving the authority.
Talk with an estate planning attorney about who should serve, when the authority becomes effective, whether backups should be named, and whether additional safeguards make sense for your situation. It is also important that family members know a plan exists and understand whom to contact if concerns arise.
5. Watch for Changes in People, Not Just Accounts
Sometimes the first warning sign isn’t a strange transaction. It’s a change in behavior.
A parent suddenly doesn’t want to discuss finances. A new acquaintance becomes unusually involved. Someone begins discouraging contact with family. There are unexplained gifts or withdrawals. Longstanding financial or estate plans suddenly change. None of these automatically means someone is being exploited. They are reasons to ask questions.
This is also where longstanding relationships with an advisor, CPA or estate planning attorney can be valuable. Those professionals may know the family, understand the financial history and recognize when something seems significantly out of character.
Adult children don’t necessarily need access to Mom and Dad’s financial information today. They should know whom to call if something changes tomorrow.
Protect Independence, Don’t Take It Away
There’s a tendency to think these conversations should happen only when someone starts having trouble. We’d rather see families have them much earlier.
Parents can decide how they want things handled. Adult children can understand what role, if any, their parents want them to play. Together, families can put legal documents in place, name trusted contacts, establish safeguards and make introductions to the professionals involved.
Then everyone can get back to living their lives.
The goal isn’t to take away independence. It’s to build enough protection around it so that it can last as long as possible.
“Should I Just Put My Adult Child on My Accounts?”
Not necessarily.
Adding an adult child as a joint owner may sound like the simplest way to make sure someone can help. However, joint ownership can unintentionally change who owns or controls the assets and how assets pass at death and potentially expose assets to the child’s creditors or other financial issues.
Often, the better question is:
What are we actually trying to accomplish?
If the goal is simply to create a safety net, then trusted contacts, account alerts, a properly drafted Power of Attorney and coordination with family members and professional advisors may accomplish that without changing account ownership.
If you’re starting to think about these issues for your parents—or yourself—we’re happy to help your family start the conversation.